01
Special Needs Trusts
We establish and customize special needs trusts that protect assets while maintaining eligibility for Medicaid, SSI, and other benefits.
Providing Security and Support for Your Loved Ones
Caring for a loved one with special needs requires careful legal and financial planning to ensure their long-term security and well-being. At Ravenell Law, we help families establish comprehensive special needs plans that protect assets, secure essential benefits, and provide ongoing support.
Request a Free ConsultationSpecial needs planning goes beyond financial considerations—it's about providing peace of mind for the future.
01
We establish and customize special needs trusts that protect assets while maintaining eligibility for Medicaid, SSI, and other benefits.
02
If your loved one requires legal protection, we assist in establishing guardianships and conservatorships to ensure their interests are safeguarded.
03
We help families navigate complex eligibility requirements for SSI, Medicaid, and other critical benefits, ensuring long-term financial stability.
Needs-based programs such as SSI and Medicaid look closely at what a person owns. The federal rules below are the starting point for most plans in Pennsylvania and New Jersey. This is general information, not legal advice; how the rules apply depends on your family's circumstances.
Supplemental Security Income (SSI) generally is not available to a person whose countable resources exceed $2,000, or $3,000 for an individual with a spouse. The Social Security Administration notes that these statutory limits have not changed since January 1, 1989.
Because the limit is so low, a modest inheritance, lawsuit recovery, or savings account left directly to a loved one can interrupt benefits. Special needs trusts and ABLE accounts are two of the main tools used to hold funds without counting them against this limit.
A first-party (self-settled) special needs trust holds the beneficiary's own assets. Under 42 U.S.C. § 1396p(d)(4)(A), it must be for a disabled individual under age 65, may be established by the individual, a parent, grandparent, legal guardian, or a court, and must repay the State for Medicaid benefits paid once the beneficiary dies.
A third-party special needs trust holds assets contributed by parents, grandparents, or others. Because the funds never belonged to the beneficiary, it is typically not subject to that Medicaid payback requirement, which makes it a common choice in a parent's estate plan.
Federal law also recognizes pooled trusts run by nonprofit associations under 42 U.S.C. § 1396p(d)(4)(C), which can be an option when a stand-alone trust is impractical.
An ABLE (Achieving a Better Life Experience) account is a tax-advantaged account that a person with a disability can use for qualified disability expenses. For SSI purposes, the Social Security Administration excludes up to $100,000 of an ABLE account balance from the beneficiary's resources.
Starting January 1, 2026, a person is eligible if their blindness or disability began before their 46th birthday. Before that date, the condition had to begin before age 26. Families who were previously shut out may now qualify, and an ABLE account can work alongside a special needs trust.
Areas We Serve
Elkins Park, Pennsylvania · New Jersey
Related Resources
A special needs trust allows you to set aside assets for your loved one without disqualifying them from essential government benefits.
Yes, but without proper planning, a direct inheritance could disqualify them from benefits. A properly structured special needs trust ensures financial security without jeopardizing eligibility.
A first-party trust holds the beneficiary's own assets, such as an inheritance or settlement paid to them. Under 42 U.S.C. § 1396p(d)(4)(A) it must be for a disabled person under age 65 and must repay the State for Medicaid benefits after the beneficiary's death. A third-party trust holds assets from family members and is typically not subject to that payback requirement.
Often, yes. The two tools serve different purposes, and many families use both. Beginning January 1, 2026, ABLE eligibility extends to people whose disability began before age 46, and the Social Security Administration excludes up to $100,000 of an ABLE balance from SSI resources. We can review whether an ABLE account fits alongside your trust.
The sooner, the better. Early planning allows for greater flexibility and ensures the best possible future for your loved one.
Ravenell Law
Ready to discuss special needs planning?
Get in Touch
With Ravenell Law, you gain more than legal services—you gain a trusted partner. Let us help you navigate the complexities of estate planning and elder law with solutions tailored to your unique goals.
Visit Us
8033 Old York Road, Ste 206
Elkins Park, PA 19027
Contact Us
(215) 935-6277Hours
Mon – Fri, 9:00am – 6:00pm
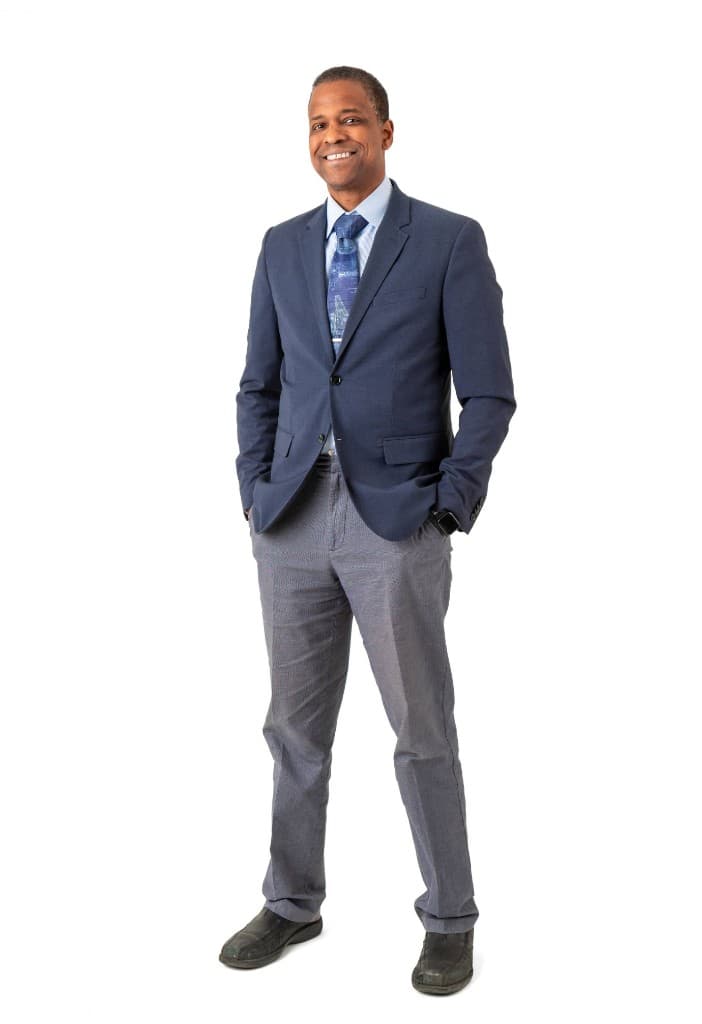
William S. Ravenell
Founder & Lead Attorney
