01
Medicaid Eligibility & Application Assistance
We help you understand Medicaid requirements and guide you through the application process to maximize your benefits while preserving your assets.
Protect Your Assets While Securing Quality Care
Planning for long-term care can be overwhelming, but it doesn't have to be. At Ravenell Law, we help families protect their assets while ensuring access to the care they need.
Request a Free ConsultationLong-term care can be expensive, and without the right planning, it can quickly deplete your assets. Our legal strategies help you protect what you've worked hard for while securing the medical care you deserve.
01
We help you understand Medicaid requirements and guide you through the application process to maximize your benefits while preserving your assets.
02
Our team provides legal solutions to safeguard your home, savings, and other assets from being consumed by long-term care expenses.
03
We work with families to create financial and legal strategies that ensure quality care while maintaining financial stability.
Medicaid coverage for nursing home and other long-term care follows federal rules that Pennsylvania and New Jersey apply through their own programs. The points below are the starting point for most plans. This is general information, not legal advice; how the rules apply depends on your family's assets, income, and care needs.
When someone applies for Medicaid long-term care, the State reviews gifts and other transfers made for less than fair market value. Under 42 U.S.C. § 1396p(c)(1)(B), the look-back date is 60 months before the application for any transfer made on or after February 8, 2006.
A transfer inside that window can trigger a penalty period. For those transfers, the penalty generally starts on the later of the month of the transfer or the date the person would otherwise be eligible and receiving institutional-level care. Penalties often start only after savings have already been spent down, so a gift to a child made in the years before care is needed should be reviewed before anyone applies.
Federal spousal impoverishment rules let the spouse who stays at home keep part of the couple's resources and income. For 2026, the Centers for Medicare & Medicaid Services lists a community spouse resource standard of $32,532 minimum and $162,660 maximum, effective January 1, 2026.
The minimum monthly maintenance needs allowance for the at-home spouse is $2,705.00 in most states, including Pennsylvania and New Jersey, effective July 1, 2026, and the maximum is $4,066.50. How a couple's assets are counted and divided is one of the main reasons married households plan before an application.
A home is not automatically protected. Under 42 U.S.C. § 1396p(f), a person generally cannot qualify for long-term care Medicaid if their home equity exceeds a limit set by the State. CMS lists the 2026 home equity limits as $752,000 minimum and $1,130,000 maximum. That limit does not apply when a spouse, a child under 21, or a blind or disabled child lawfully lives in the home.
After death, 42 U.S.C. § 1396p(b) requires the State to seek recovery from the estate of a person who was 55 or older when they received nursing facility services, home and community-based services, and related hospital and prescription drug services. Federal law limits when recovery can happen, for example while a surviving spouse is living. Planning for the home is often about both eligibility and what happens to it later.
In Pennsylvania, Community HealthChoices (CHC) is the long-term services and supports managed care program for people eligible for both Medicaid and Medicare, and for individuals 21 or older with physical disabilities. Applications go through the local county assistance office.
In New Jersey, Managed Long Term Services and Supports (MLTSS) delivers long-term services and supports through NJ FamilyCare managed care organizations, with a clinical eligibility determination made through the Division of Aging Services. Which plan covers a particular facility or in-home provider is worth checking before a placement decision.
Areas We Serve
Willow Grove, Pennsylvania · New Jersey · Voorhees Township
Related Resources
Medicaid planning involves legal and financial strategies to help individuals qualify for Medicaid while preserving assets. We create customized approaches that meet eligibility requirements without sacrificing financial security.
We recommend starting before care is required—ideally by your 50s or 60s. Early planning opens up more options and better protects assets.
Yes. While estate planning focuses on asset distribution after death, Medicaid planning centers on maintaining eligibility while preparing for long-term care expenses during your lifetime.
For transfers made on or after February 8, 2006, federal law looks back 60 months (five years) from the Medicaid application for gifts or transfers made for less than fair market value. A transfer inside that window can delay eligibility for long-term care coverage. We review past transfers before an application is filed.
Sometimes. Home equity above the State's limit generally bars long-term care Medicaid, and CMS lists the 2026 limits as $752,000 minimum and $1,130,000 maximum. The limit does not apply when a spouse, a child under 21, or a blind or disabled child lives in the home. Estate recovery rules may still reach the home later, so we look at both questions together.
Ravenell Law
Ready to discuss medicaid & long-term care planning?
Get in Touch
With Ravenell Law, you gain more than legal services—you gain a trusted partner. Let us help you navigate the complexities of estate planning and elder law with solutions tailored to your unique goals.
Visit Us
8033 Old York Road, Ste 206
Elkins Park, PA 19027
Contact Us
(215) 935-6277Hours
Mon – Fri, 9:00am – 6:00pm
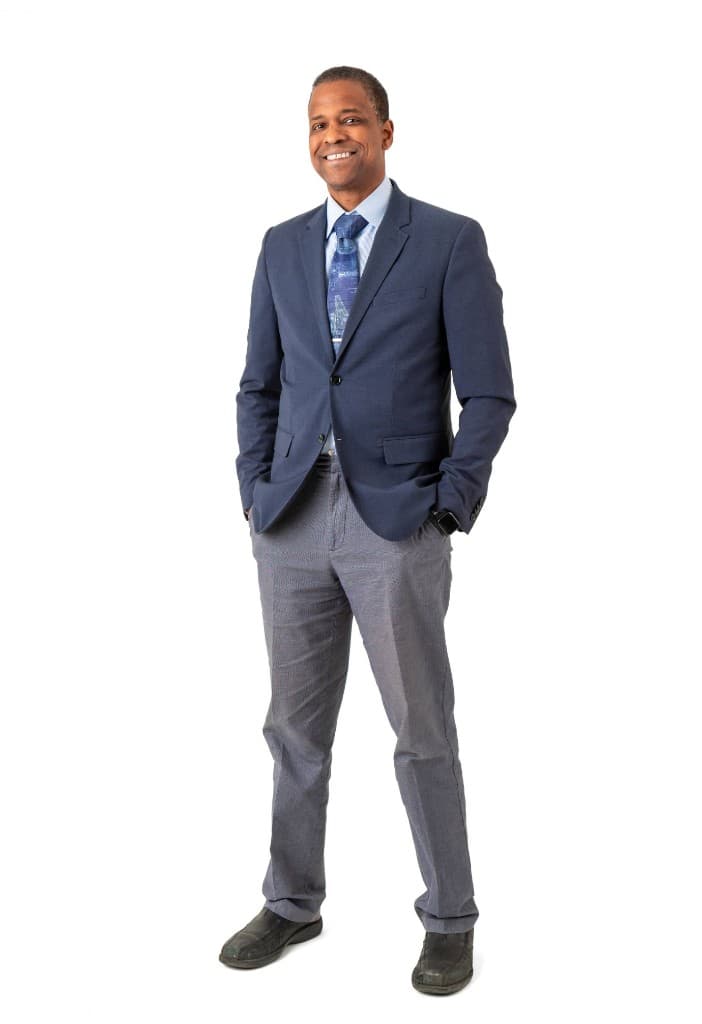
William S. Ravenell
Founder & Lead Attorney
